

January Jumpstart: Retail Planning for Q1 Success
January Jumpstart: Retail Planning for Q1 Success
The festive season has drawn to a close, and the tinsel has been packed away. Now, as a UK retailer, it's time to turn your attention to Q1 planning. January might seem like a quiet month, but it's the perfect opportunity to strategically prepare for the months ahead and set the stage for a successful year. This comprehensive guide will provide you with actionable steps to optimise your operations, boost sales, and make the most of the first quarter.
Assessing the Holiday Season Performance
Before diving into Q1 planning, take a step back and analyse your performance during the crucial holiday season. This evaluation will provide valuable insights into what worked well and what areas need improvement.
Key Performance Indicators (KPIs) to Review:
- Sales Figures: Compare your sales data to previous years to identify trends and growth areas.
- Website Traffic: Analyse website traffic to understand customer behaviour and identify popular products or pages.
- Conversion Rates: Assess your conversion rates to determine the effectiveness of your marketing campaigns and website design.
- Customer Feedback: Review customer reviews and feedback to understand customer satisfaction and identify areas for improvement.
- Inventory Management: Evaluate your inventory turnover and identify any stockouts or overstock situations.
By thoroughly analysing these KPIs, you can gain a clear understanding of your strengths and weaknesses, allowing you to make informed decisions for Q1 and beyond.
Setting Realistic Q1 Goals
With a clear understanding of your holiday season performance, you can now set realistic and achievable goals for Q1. These goals should be specific, measurable, achievable, relevant, and time-bound (SMART).
Examples of SMART Goals:
- Increase online sales by 15% compared to Q1 of the previous year.
- Improve customer satisfaction scores by 10% by implementing a new customer service initiative.
- Reduce inventory holding costs by 5% by optimising inventory management practices.
- Launch a new product line focused on household products by the end of February.
Ensure your goals align with your overall business objectives and that you have a clear plan in place to achieve them. Communicate these goals to your team to ensure everyone is working towards the same objectives.
Optimising Inventory Management
Effective inventory management is crucial for maximising profitability and minimising waste. Q1 presents an excellent opportunity to optimise your inventory practices and ensure you have the right products in stock at the right time.
Strategies for Inventory Optimisation:
- Demand Forecasting: Use historical data and market trends to accurately forecast demand for your products.
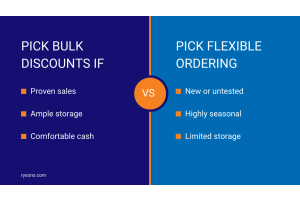
- Just-in-Time (JIT) Inventory: Implement a JIT inventory system to minimise holding costs and reduce the risk of obsolescence.
- ABC Analysis: Classify your inventory based on its value and importance, focusing on managing your high-value items more closely.
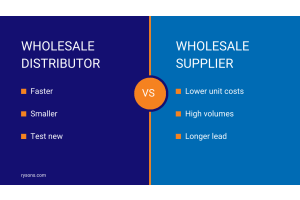
- Supplier Relationships: Build strong relationships with your suppliers to ensure timely delivery and favourable pricing. Consider sourcing essential cleaning products for your business.
- Regular Stock Audits: Conduct regular stock audits to identify discrepancies and prevent stockouts or overstock situations.
By implementing these strategies, you can reduce inventory holding costs, improve order fulfilment rates, and enhance customer satisfaction.
Revamping Your Marketing Strategy
Q1 is an ideal time to refresh your marketing strategy and attract new customers. Consider the following tactics:
Effective Marketing Tactics for Q1:
- Post-Holiday Sales: Offer attractive discounts and promotions to clear out remaining holiday inventory and attract bargain hunters.
- Targeted Email Marketing: Segment your email list and send targeted messages to specific customer groups based on their interests and purchase history.
- Social Media Engagement: Engage with your followers on social media by running contests, sharing relevant content, and responding to customer inquiries.
- Content Marketing: Create valuable content, such as blog posts, articles, and videos, to attract potential customers and establish yourself as an industry expert.
- Partnerships: Collaborate with other businesses to reach new audiences and cross-promote your products or services. Consider offering bundled deals with complementary products like kitchen items.
Remember to track the performance of your marketing campaigns and make adjustments as needed to maximise your return on investment.
Focusing on Customer Experience
Providing exceptional customer service is essential for building loyalty and driving repeat business. Use Q1 to enhance your customer experience and create a positive impression on your customers.
Strategies for Enhancing Customer Experience:
- Personalised Service: Provide personalised recommendations and offers based on customer preferences and purchase history.
- Easy Returns and Exchanges: Offer hassle-free returns and exchanges to build trust and encourage repeat purchases.
- Proactive Communication: Keep customers informed about their orders and any potential delays.
- Customer Feedback: Actively solicit customer feedback and use it to improve your products and services. You can even ask for feedback on garden supplies if that is relevant to your business.
- Loyalty Programs: Reward loyal customers with exclusive discounts, early access to new products, and other perks.
By prioritising customer experience, you can build strong relationships with your customers and create a loyal customer base.
Staff Training and Development
Investing in staff training and development is essential for improving employee performance and enhancing customer service. Q1 is a good time to schedule training sessions and equip your team with the skills and knowledge they need to succeed.
Areas for Staff Training:
- Product Knowledge: Provide comprehensive training on your products and services.
- Sales Techniques: Teach your staff effective sales techniques to increase conversion rates.
- Customer Service Skills: Train your staff on how to handle customer inquiries and complaints effectively.
- Technical Skills: Provide training on any new software or technologies your business is using.
Ensure your training programs are engaging and relevant to your employees' roles. Consider offering incentives for completing training and achieving performance goals.
Streamlining Operations
Efficiency is key to profitability. Use Q1 to streamline your business operations and identify areas where you can improve efficiency and reduce costs.
Areas for Operational Improvement:
- Automation: Automate repetitive tasks to free up your staff to focus on more strategic activities.
- Process Optimisation: Review your business processes and identify areas where you can eliminate waste and improve efficiency.
- Technology Adoption: Invest in new technologies that can help you streamline your operations and improve productivity.
- Supply Chain Management: Optimise your supply chain to reduce lead times and improve inventory management.
By streamlining your operations, you can reduce costs, improve efficiency, and enhance your competitiveness.
Financial Planning and Budgeting
Q1 is also a crucial time for financial planning and budgeting. Review your financial performance from the previous year and create a realistic budget for the coming year.
Key Financial Planning Activities:
- Revenue Forecasting: Forecast your revenue based on historical data and market trends.
- Expense Budgeting: Create a detailed budget for all your expenses, including marketing, inventory, and staffing.
- Cash Flow Management: Manage your cash flow effectively to ensure you have enough funds to cover your expenses.
- Profitability Analysis: Analyse your profitability to identify areas where you can improve your margins.
Regularly monitor your financial performance and make adjustments to your budget as needed. Consider investing in storage solutions to better manage your inventory and reduce potential losses.
Staying Ahead of Trends
The retail landscape is constantly evolving, so it's important to stay ahead of the latest trends and adapt your business accordingly. Keep an eye on emerging technologies, changing consumer preferences, and new competitors.
Strategies for Staying Ahead of Trends:
- Industry Publications: Subscribe to industry publications and attend industry events to stay informed about the latest trends.
- Market Research: Conduct market research to understand consumer preferences and identify new opportunities.
- Competitor Analysis: Monitor your competitors' activities to identify their strengths and weaknesses.
- Experimentation: Experiment with new technologies and marketing strategies to see what works best for your business.
By staying ahead of the trends, you can position your business for long-term success.
By implementing these strategies, you can effectively plan for Q1 and set your retail business up for a successful year. Remember to regularly monitor your progress and make adjustments as needed. Good luck!
Ready to take your retail business to the next level? Explore a wide range of wholesale products and discover exclusive deals at Rysons.com today!